The Tokenized

Real World Asset tokenisation, decoded.

Writing on what's actually happening in tokenised finance, from someone who reads the regulations, not just the launch tweets.

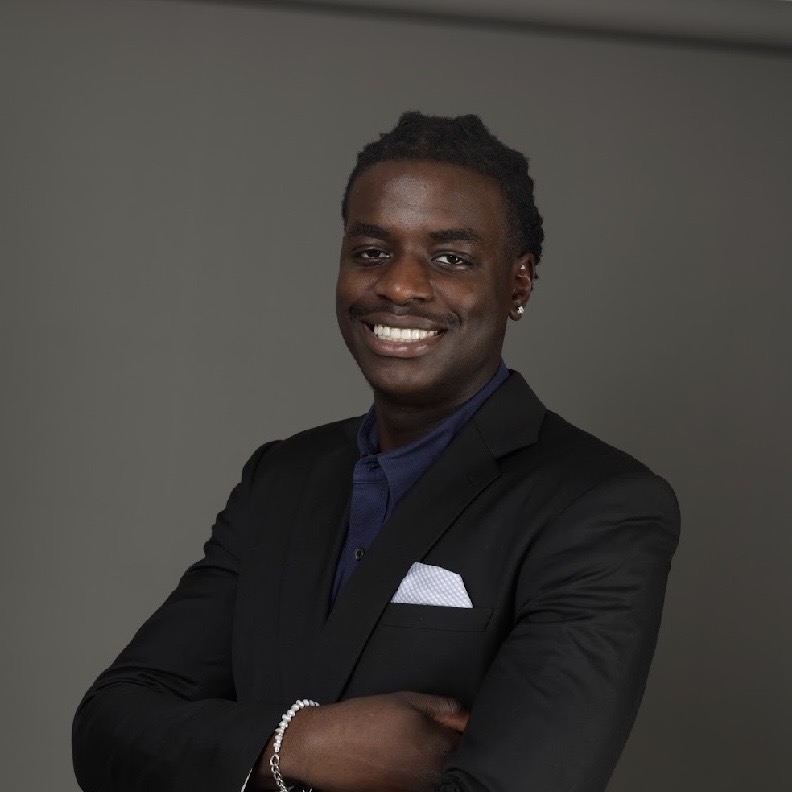
Ayomikun Akin-Bankole

About

I am Ayomikun Akin-Bankole. My interest in Real World Asset tokenisation grew out of a single observation: the most consequential shift in modern finance, the gradual migration of regulated assets onto programmable infrastructure, is being narrated almost entirely by people with something to sell. The Tokenized is my attempt to correct that, written for the operators, asset managers, and advisers who will work within this market long after the launch announcements fade.

My focus falls deliberately on the parts of tokenisation that rarely make headlines. Rather than tracking token prices or speculating on the next platform launch, I examine how a tokenised treasury fund actually settles, what the FCA and MiCA frameworks require in practice, and why those mechanics matter to the fund administrator whose job is to make them work. Much of the commentary in this space conflates regulated tokenised securities with the wider world of cryptocurrencies, a distinction that appears merely technical yet in practice determines what is permissible, who is protected, and where the genuine opportunities lie. Reading the regulations, the prospectuses, and the on-chain data, rather than the marketing layered on top of them, is what lets me hold that line.

This is written for a particular reader: the fintech operator, the small or mid-sized asset manager, the independent adviser, and the platform employee who needs something sharper than a press release to think with. If that describes you, my aim is simple: to leave you understanding not merely that tokenisation is happening, but how it works and what it changes. No hype, and no claim I cannot source.

Recent writing

13 October 2026

Everyone says tokenised collateral is the prize. ESMA asked what happens on the day a clearing member defaults.

Industry told the FCA and the Bank of England that collateral is what tokenisation is for. ESMA's new call for evidence asks the harder question: whether a clearing house can turn a tokenised asset into cash, legally and on time, when a member fails. It has seen exactly one such project in EU central clearing.

Read on Substack →

8 October 2026

Three EU regulators answered the MiCA review the same way. The problem they found is not in MiCA.

The EBA, ESMA and the European System of Central Banks have all answered the Commission's MiCA review, and all three say tokenised securities belong in securities law, not crypto law. The more important part is where they locate the real problem: legal title, settlement finality, and national property law that differs from one member state to the next. A day later, the Bank of England said much the same about the UK.

Read on Substack →

30 September 2026

The Bank of England's newest tokenised depository issues wrappers. That is the point.

The coverage said the Bank of England had approved live settlement of tokenised gilts and FTSE 350 shares. The Bank's own approval notice says ClearToken will issue Tokenised Depository Interests, one for one against assets an FCA-authorised custodian holds. The UK has now licensed one native depository and one wrapper, and written the legal claim into both licences. Native versus wrapper was never the right test.

Read on Substack →

24 September 2026

The ECB just put central bank money on a ledger. Both central banks still say 2028.

The Eurosystem's Pontes went live on 21 September, settling tokenised assets in central bank money with thirteen banks and four ledger operators. The obvious read is that the euro area is years ahead of the UK. The ECB's own date for full implementation is 2028, the Bank of England's is 2028, and in both designs the payment only becomes final in the conventional settlement system.

Read on Substack →

17 September 2026

123 firms told the FCA what tokenisation is for. Atomic settlement barely came up.

The FCA and Bank of England finally published their tokenisation feedback statement. Collateral was by far the most frequently mentioned use case, and the two features that dominate every tokenisation pitch deck were rarely raised at all. The blockers industry named are an insolvency statute and the Basel framework, neither of which a better ledger fixes.

Read on Substack →

See all writing →

Work with me

I help fintech and tokenisation companies sharpen how they communicate.

LinkedIn ghostwriting for fintech & tokenisation leaders

For founders, executives, and BD leaders at fintech and tokenisation companies who need a consistent LinkedIn presence but don't have time to build one. Monthly retainer, your voice, my hours.

Research & editorial services for tokenisation companies and funds

Whitepapers, market briefings, investor narrative documents, competitive landscape research. The kind of writing that requires both finance literacy and clear thinking.

Get in touch → ayomikunaab@gmail.com